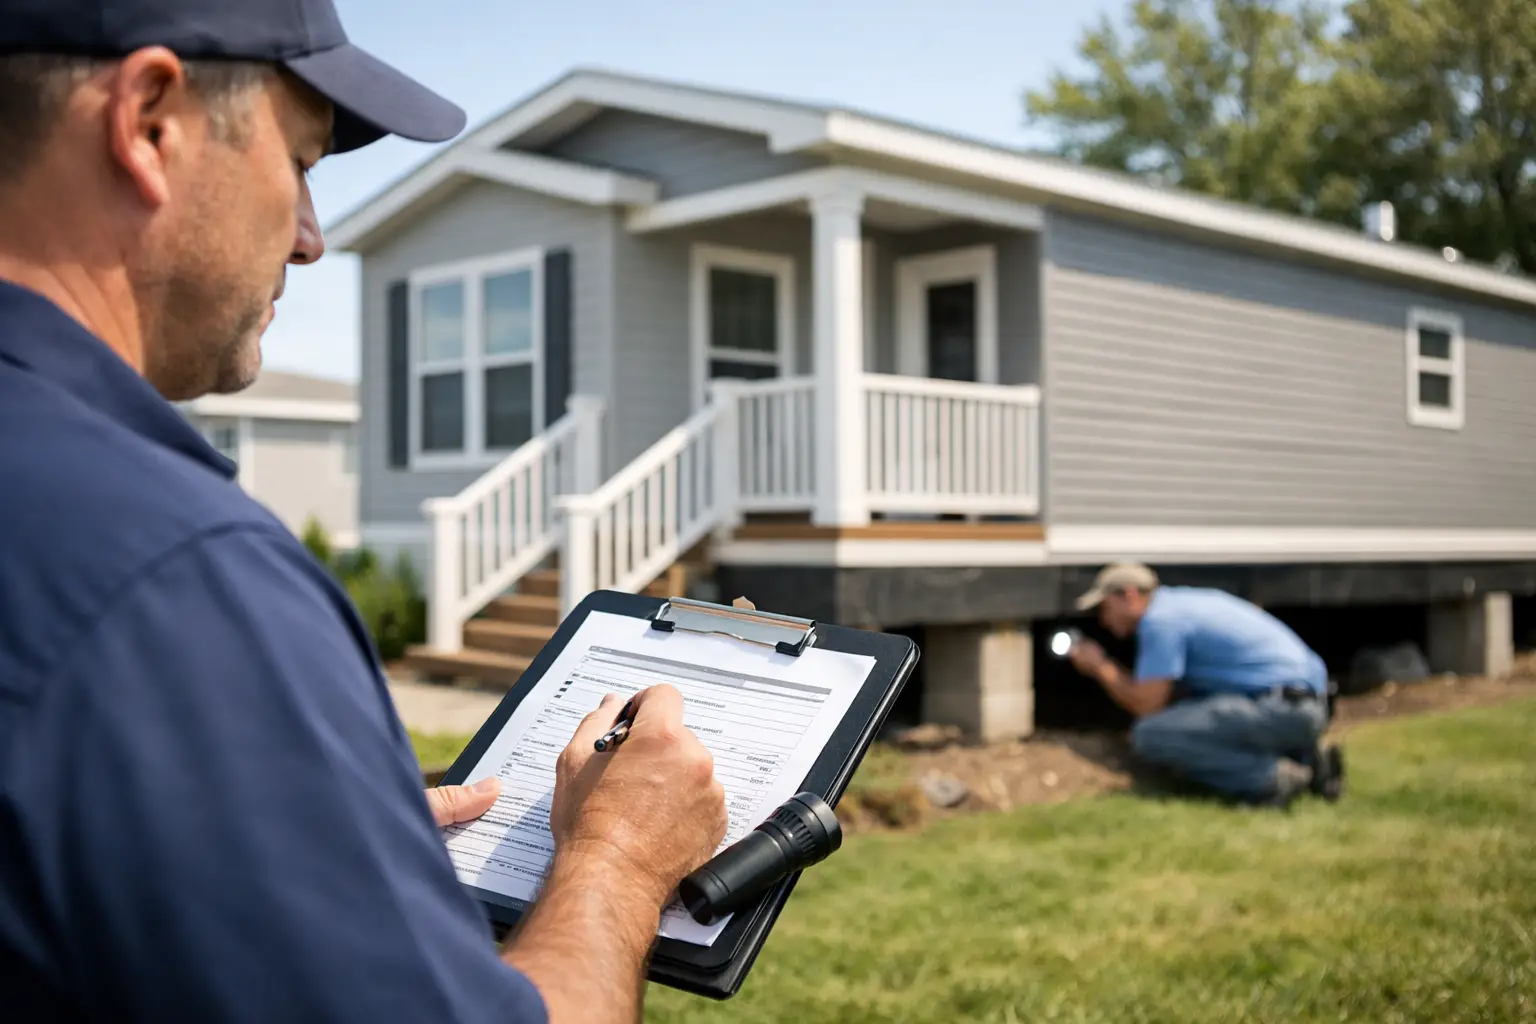
A manufactured home buyer may be days from closing when a lender asks for an inspection, a foundation certification, repairs, or all three. A manufactured home loan inspection example helps clarify what that request can mean, what an inspector is documenting, and which issues deserve attention before the loan timeline gets tight.
The first point to understand is that a loan inspection is not always the same service as a general home inspection. A general inspection evaluates the visible condition of the home and its major systems. A HUD, FHA, or VA-related inspection may focus more narrowly on loan eligibility, health and safety concerns, and whether the home appears to meet program-specific requirements. Your lender, appraiser, and loan program determine the exact documentation needed.
What a Loan Inspection Is Trying to Verify
Manufactured homes have requirements that do not apply in quite the same way to site-built homes. The age of the home, its HUD certification labels, its location, its permanent foundation, and its connection to utilities can all matter to financing.
For many FHA and VA transactions, the key question is whether the home is permanently installed and appears suitable for long-term residential use. That can involve the foundation system, tie-downs, skirting, access beneath the home, stairs, porches, electrical service, plumbing, heating, and visible safety conditions. Some loans also require an engineer’s foundation certification. A home inspector can identify visible concerns, but an engineer provides the certification when the lender requires one.
A qualified inspection report should be specific about what was observed, what could not be observed, and what needs correction or further evaluation. It should not promise loan approval. That decision belongs to the lender and, in some cases, the appraiser or underwriter.
Manufactured Home Loan Inspection Example: A Typical Scenario
Consider a double-wide manufactured home outside Bainbridge Island. It was built after the federal HUD Code took effect, sits on a privately owned lot, and is being purchased with FHA financing. The lender asks for a HUD/FHA manufactured-home compliance inspection after the appraiser notes that the crawlspace access is restricted and the front stairs lack a handrail.
The inspector begins by confirming the home’s identifying information where accessible, including the HUD certification labels and data plate. Missing labels do not automatically mean a property cannot be financed, but they can create a documentation issue that should be addressed early. The inspector also reviews the visible installation conditions around the home.
Example report observations
The report may read like this:
> The manufactured home appears to be supported by piers and perimeter blocking over a crawlspace. Visible piers appeared generally plumb from accessible areas. Due to limited crawlspace clearance and stored materials, not all support components were visible. No opinion is offered regarding compliance with an engineered foundation standard. Obtain an engineer’s foundation certification if required by the lender.
> The front entry stair assembly has four risers and lacks a graspable handrail. Install a secure handrail to reduce fall risk and satisfy typical safety expectations for loan-related repairs.
> The rear deck is connected to the home and shows localized decay at two support posts near grade. Repair or replace damaged posts and verify that the deck is adequately supported before closing.
> The electrical service panel cover was removed where safe to do so. No visible open splices were observed. One exterior receptacle tested inoperable and should be evaluated and repaired by a qualified electrician.
> Moisture staining was observed on portions of the vapor barrier beneath the primary bathroom. A moisture scan at accessible bathroom finishes did not identify elevated readings at the time of inspection. Repair any active plumbing leakage and monitor the area after repair.
This example gives the lender and buyer useful information without overstating what the inspection can prove. It identifies safety and condition concerns, distinguishes visible observations from inaccessible areas, and directs specialized questions to the appropriate professional.
What Inspectors Commonly Examine
The scope should be confirmed before the inspection, because lender requests vary. Still, a thorough manufactured-home loan inspection often includes the home’s visible structure, site conditions, and major systems.
The exterior review typically considers siding, windows, doors, roof coverings, gutters, skirting, vents, stairs, decks, porches, and grading. Skirting is more than a cosmetic detail. Missing or damaged sections can allow animals and moisture into the crawlspace, while inadequate ventilation can contribute to moisture accumulation.
Below the home, the inspector looks for accessible evidence of support issues, damaged or missing insulation, standing water, deteriorated vapor barriers, disconnected ducts, plumbing leaks, pest activity, and unsafe wiring. Crawlspaces can be difficult to access, particularly on older homes or properties with heavy storage. A careful report should explain those limitations rather than treating an obstructed area as fully inspected.
Inside, the inspection usually addresses visible walls, ceilings, floors, plumbing fixtures, electrical outlets, heating equipment, smoke alarms, and signs of water intrusion. Thermal imaging can help identify temperature patterns consistent with missing insulation or possible moisture, but it does not see through walls or diagnose mold by itself. When moisture signatures or musty odors are present, further moisture investigation or mold testing may be appropriate.
Roof access deserves the same practical judgment. When a roof can be walked safely, a hands-on inspection provides valuable detail. When roof slope, weather, height, or surface condition makes walking unsafe, drone imagery can document roof conditions without taking unnecessary risks.
Repairs That Commonly Affect Loan Timelines
Not every defect needs to be repaired before closing. Cosmetic wear, an aging countertop, or minor nail pops may matter to a buyer’s decision but are less likely to become loan conditions. Health, safety, water intrusion, and structural concerns receive more attention.
Common lender-related repair requests include missing handrails, exposed electrical wiring, broken windows, active roof leaks, nonfunctioning heating during cold weather, trip hazards, damaged steps, unsafe deck conditions, and serious moisture or pest damage. An appraiser may flag a concern independently of the inspection, so it is wise to address obvious issues before the appraisal when possible.
Foundation questions require special care. A manufactured home may look stable while still lacking documentation required by a particular loan program. Conversely, an inspector may observe no visible defect but still recommend an engineer’s certification because the lender requires formal verification. The right path depends on the loan program, the property’s ownership arrangement, the home’s age, and the lender’s underwriting standards.
How Buyers and Sellers Can Prepare
The simplest preparation often prevents the most expensive delays. Make sure the crawlspace access is open, remove stored items that block the entry, and provide access to the electrical panel, furnace, water heater, and attic areas. If the home has HUD labels or installation records, gather them before the inspection.
Sellers should repair straightforward safety issues early, especially loose stairs, missing rails, broken fixtures, visible leaks, and exposed wiring. Buyers should read the report with their agent and lender, separating immediate loan conditions from longer-term maintenance planning. A detailed report can help everyone have a more focused repair conversation.
For manufactured-home transactions in Kitsap County and surrounding areas, specialized experience matters because the inspection must balance practical property condition with the documentation lenders expect. Lavalyn Inspections uses a detail-intensive process, including thermal imaging and safe roof documentation, to provide clear findings and reports within 24 hours when transaction timing demands it.
A loan inspection should leave you with more than a list of defects. It should show what is visible, identify what needs prompt action, and give you a clear next step when a lender, engineer, electrician, or repair contractor needs to be involved. That clarity is often what keeps a manageable repair from becoming a closing-day surprise.


Leave a Reply